Investment Overview · 2026
The Operating System for Private Markets
Intelligence is universally needed, yet no one has built the infrastructure to deliver it at institutional quality and speed. Crossover Intelligence is the AI-native platform that turns verbatim customer truth into decision-ready signal for enterprises, banks, funds, and operators. We've built the intelligence infrastructure that lets organizations extract, digest, and activate customer insight within their businesses. The model works, the clients pay, and the data compounds with every engagement. Built bootstrapped, without outside capital. This raise is about speed and scale. Not survival.
First meeting: this page, then Traction, then The Raise. Platform and Market are the deep end, built for the second conversation.
130+
Proprietary intelligence engagements
Every study feeds the compounding data asset
9
Core metrics captured per study
The benchmark standard for private software
30–50
Decision-makers per study
Verbatim truth, not paid expert opinion
2.5–4 wks
Study turnaround
vs. 8–10 consultant weeks
36
Production workflows
The deal lifecycle, dispatchable: one-step scans to full-mandate chains
The Founder
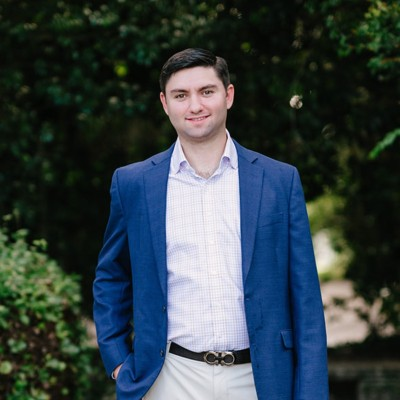
He invented the mechanism. Crossover industrialized it.
Brad Lyons, Founder and Chief Executive Officer · Co-Founder, BWG Strategy
Built it
Co-founded BWG Strategy and built a different kind of research firm. Not brokered expert calls, but convened panels: the operators and decision-makers who move a market in one room, with Brad leading the discussion. Speakers came for free, because ten minutes of talking bought fifty minutes of listening, so the model carried almost no cost of goods. 200+ top TMT hedge funds subscribed, 60 employees, and a $92M recapitalization in 2020.
The same mechanism, aimed at private markets
Crossover runs that model for private markets, with a platform on top. The fieldwork is multi-respondent by construction rather than one brokered call at a time, which is why an engagement produces an answer instead of a library of transcripts. The mechanism was proven by hand before any of it was automated.
And the operator who industrialized it
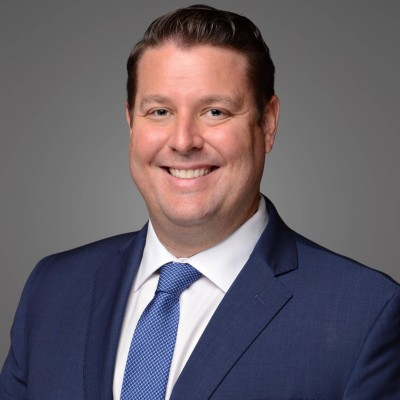
Christopher Lynas
Partner and Chief Operating Officer · MBA, NYU Stern
Institutional clients are not buying a study, they are buying the assurance that the next one is run the same way. Christopher owns that: delivery, the standard every engagement is held to, and the financial infrastructure underneath it.
Eight years as a naval aviator, most of it instructing and then in test and evaluation, where nothing reaches the fleet until someone has proven it holds up. Same discipline, different consequences. Getting it right the first time is fast enough.
Right in public, on the record
“In August I wrote a thesis I never published. The funds I was warning were key Crossover Research clients, so I stayed quiet. Since then, software multiples are down 50%+. The SaaSpocalypse arrived.”
“PLTR’s data abstraction and ontology model, which is considered a critical component, creates a compelling competitive moat vs. SNOW and Databricks.”
He held the software call because the funds he would have been warning were clients. Both halves of that sentence are the business. The Palantir note runs on operator checks, a proprietary customer survey, and verbatims attributed by title and company type rather than by name: the house standard, in public, two years before this raise.
Selected calls, each grounded in operator checks
Oct 2023
$AXON · $TYL
Named public-sector software as a durable theme. It is the spine of the 2026 regulatory-moat thesis.
readDec 2023
$VRT
Called Vertiv the share gainer in data-center infrastructure against Schneider and Eaton.
readTwenty-plus companies covered in long-form public write-ups across software, fintech, consumer, and industrials.
Index post.
200+
TMT hedge funds served
Follower and view counts as of July 2026.
01
The structural problem
Private B2B software markets run on fundamental information asymmetry.
$8.9T
Private market AUM, 2024
Near zero standardized disclosure. Every data point sourced from scratch
6–12 wks
Typical diligence cycle
Consultant-led CDD; relationship-gated, slow, and repriced at every mandate
Public markets have standardized disclosure and real-time data infrastructure. Private market participants navigate fragmented information, relationship-dependent deal flow, and protracted diligence cycles. The result: impaired capital allocation, extended timelines, and constrained returns across the ecosystem. The sponsor who pays 14x without understanding the customer base destroys more value than the sponsor who pays 12x with conviction. Misallocated capital is the cost of missing evidence.
6.6–7 yrs
Avg. GP hold period, 2025
52% of global buyout inventory held 4+ yrs, a record; 63%+ in North America
$115B
GP-led secondaries, 2025
Up 53% YoY, now 48% of all secondary activity, vs. just 19% in 2014
Traditional exits, IPOs and strategic M&A, have stalled. GPs are sitting on a record backlog of 31–32K unsold portfolio companies worth $3.7–3.8T, with no clean path out. CVs now account for 87% of GP-led secondary volume and ~19% of all sponsor-backed exits in H1 2025, and the diligence burden has never been higher.
02
The Wedge
We find the people whose opinions actually move a B2B SaaS deal, create the forum where they share the reasoning that matters, and turn it into an IC-ready read in days.
01 · Access
Every participant is screened before they contribute a word. We verify role, budget ownership, and deal involvement, so the fieldwork starts at the level expert networks charge extra to reach.
02 · Discovery
Structured interviews, not survey checkboxes. Participants share the reasoning behind the decision: why they bought, what almost killed the deal, and what they would change about the product today.
03 · Synthesis
An actionable, synthesized, IC-ready report, a focused read in days once fieldwork closes; a full CDD in 2.5–4 weeks against 8–10 consultant weeks.
The data quality standard
We only collect signal from budget owners, decision-makers, and C-suite. The people deal flow actually depends on.
Not IT managers. Not mid-level evaluators. Not paid expert opinion.
100%
Verified budget owners or C-suite per study
30–50
Decision-maker voices per study
130+
Proprietary engagements in the corpus
Senior-weighted voice of customer
Of 5,200+ interviews, among respondents with captured titles:
C-suite / Founder / Partner49%
Other / Individual contributor20%
58% of titled respondents are VP-level and above. Analysis is weighted by seniority tier via Cortex.
03
Proof in the market
Three transactions we can name publicly. $11.2B in disclosed transaction value, a floor not a ceiling. One intelligence layer underneath all of them.
 ·Series C
Cross-party intelligence$500M
Sell-side mandate pitch
J.P. Morgan commissioned our research to differentiate their Series C mandate pitch. We interviewed 30+ customers. They won the exclusive mandate.
Outcome
Won the exclusive sell-side mandate
Buy-side diligence
Our research flagged Nerdio as an exceptional asset. General Atlantic commissioned deeper diligence to build conviction before bidding.
Outcome
$500M investment at unicorn valuation
The takeawayWe powered both sides of the same transaction with the same underlying customer truth. This is cross-party intelligence: not a PE DD shop, not a consultancy. The intelligence layer sits above the transaction.
Mandate Pitch$10B
Sell-side mandate pitch
“Having a Voice of Customer document was seen as a differentiator by the client. The findings from your report were a key part of the equity story materials we presented.”
Executive Director, J.P. Morgan
Outcome
VoC report cited as the mandate-winning differentiator
Acquisition$675M
CIM enhancement
Independent customer research strengthened the CIM narrative and gave management a defensible equity story ahead of the Zscaler acquisition. Every customer claim pre-validated with no surprises in diligence.
Outcome
$675M exit. CIM backed by independent customer evidence
04
Research product → intelligence platform
The transition from project-based vendor to embedded corporate intelligence infrastructure, and why it expands the TAM by an order of magnitude.
Without platform
Research Firm
Client perception“Another VoC provider”
Buying decisionProject-by-project evaluation
Competes withGLG, Third Bridge, boutique consultants
RelationshipVendor, replaceable
TAMPE CDD market ($2–4B)
With platform
Corporate Intelligence Infrastructure
Client perception“Intelligence infrastructure for private markets”
Buying decisionStrategic partnership evaluation
Competes withBloomberg, Carta: category creators
RelationshipPartner, embedded with switching costs
TAM$150B+ global insights industry (ESOMAR 2024)
The Palantir playbook
Wrong model
500 funds at $50K
Broad market · feature bloat · commoditized over time
Right model
15–20 tier-1 funds at $500K–$1M ACV
Elite tier only · white-glove · moat compounds faster
Our moat is premium-focused, not scale-focused. Tier-1 funds value exclusivity and pay for edge. 20 clients at $750K average outperforms 500 clients at $50K, and is executable with the team we have.
05
From a family side-project to intelligence infrastructure
Three phases, one instinct: there had to be a better way to get at the truth in a market. Consultants first, then operators, now a platform.
Phase IProve the craft2023 – Mid-2024
A decade inside institutional research said VoC was broken. Prove the better way by hand, profitably, before writing a line of code.
2023
Four brothers, part-time
Brad and his brothers: 10+ years in institutional research, consulting on B2B SaaS nights and weekends.
2023
A better way
Transcripts and expert calls aren't answers. The thesis: the informed voices that move a deal, synthesized to decision-ready.
Feb 2024
First engagements
First revenue lands February 1, 2024. The format has demand, and it's profitable from day one.
Phase IIThe signalSep 2024 – May 2025
One transaction reveals the asset isn't the report. It's the intelligence underneath: standardized, accessible, serving every side of the market.
Sep 2024
Both sides of a $500M deal
J.P. Morgan engages us for the Nerdio mandate pitch; General Atlantic commissions the buy side in November. Same customer truth, both sides of the transaction.
Fall 2024
Hired Chris Lynas
First hire beyond the founding four: a COO to build the operating and financial infrastructure under the growth.
2024–25
Built Cortex to scale
The discovery engine that finds the people whose opinions actually matter, systematized.
May 2025
First Catalyst intelligence sale
BlueCat customer truth, repackaged as buy-side intelligence for Francisco Partners. One corpus, two products, two invoices.
Phase IIIBecome the platform2025 – Now
Demand outran the manual process. We bought the tools, hit their ceilings, and built the operating system ourselves.
2025
Bought the stopgaps
Grunt for Excel-to-slides: the first ceiling, static deliverables.
2025
Frontier models, firsthand
Anthropic's Claude for Finance advisors beta, top 1% of users, and a clear view of what bare LLMs can't do alone.
2026
Outgrew PowerPoint
Deliverables become hosted, password-gated intelligence sites, like this one.
2026
Built the OS ourselves
The Command Center we run the firm on every day: 36 production workflows executing real mandates. Researchers who ship software.
Now
Ready to scale
$15M to build the corporate intelligence infrastructure across three parallel markets. Two years of profitable services proved the model.
06
The thirty-second version
The intelligence layer is universally needed, and no one has built the infrastructure to deliver it at this quality and speed. We have: 130+ engagements, 30 institutional clients, and both sides of the same $500M deal trusting one customer truth. GLG and Tegus sell you transcripts. We sell you the answer. We are not a research firm. We are the corporate intelligence layer that sits above the deal.
The manual version proved the model. The raise turns it into infrastructure.